Starting early, and the 529 plan
The first time Brooke met Myles, school waiting lists, and the US account every UK-connected family should understand.
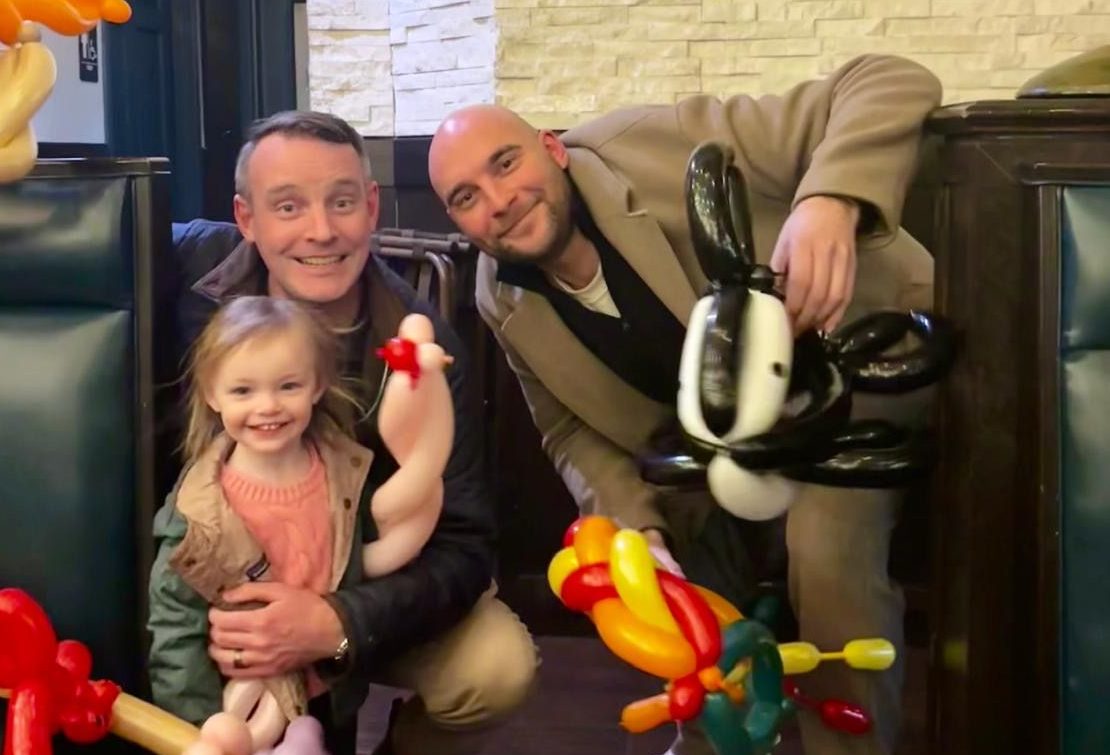
This was the first time Brooke met Myles, and for me, that mattered.
When you build a business with someone, you spend hours discussing strategy and clients. But welcoming them into your world outside the office is different.
At one point, I mentioned we had been looking at schools before she was born.
Myles stopped me. “Before she was born?”
I wasn’t joking.
We laughed about how early parents start thinking about admissions and waiting lists. It sounds excessive until you realise how quickly the years pass.
In financial planning, starting early is rarely about urgency. It is about optionality.
Education is one of the few milestones that arrives on schedule. You do not delay it five years because markets were volatile.
For many families in the US, that early planning begins with a 529 plan.
What a 529 plan is
A 529 plan is a US education investment account designed to fund future schooling costs.
For those more familiar with the UK system, think of it as ring-fencing investments for tuition in a tax-advantaged structure.
You contribute after-tax dollars. Investments grow free of federal, and generally state, tax when used for qualified education expenses.
Some states offer an income tax deduction or credit. Rules vary, and in some cases benefits apply only if you use that state’s plan.
Setting one up is straightforward. You open an account through a state-sponsored 529 platform.
Key questions to consider
- Does my state offer a tax deduction, and do I need to use its plan to receive it?
- What are the investment options and fees?
- If we move states, how portable is the account?
- Does the state offer enhanced benefits, such as prepaid tuition programs?
- Could our child study outside the US, and which structure best supports that?
The state of registration does not determine where your child can attend school. It mainly affects tax treatment and structure.
But what if things change?
A 529 is more flexible than many realise.
You can change the beneficiary, use it for graduate education, roll a portion into a Roth IRA subject to rules, or withdraw funds and only pay tax and penalty on the gains portion.
A 529 can be used at eligible foreign universities that participate in the US federal student aid system. Many UK and European institutions qualify.
This is often overlooked, and sometimes misunderstood by UK-connected families who assume a 529 only makes sense if they plan to remain in the US long term.